The record
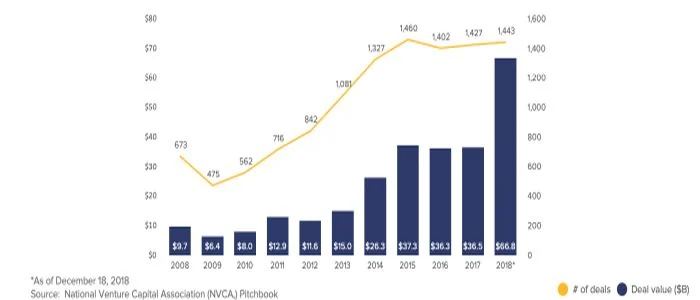
Corporate investors took part in 2,765 of the 15,240 US venture deals the National Venture Capital Association's own 2026 Yearbook data pack records for 2024, 18% of deal count, but those deals carried $118.52 billion of the year's $211.48 billion in total capital raised, or 56% of dollars. In 2025 the same table shows corporate involvement in 16% of deals by count but 58% by dollars, $184.60 billion of $319.97 billion. NVCA's own Yearbook landing page, describing 2025, states that AI-era capital was 'fueled by corporate strategics and sovereign wealth funds,' without giving a separate percentage for each investor type.
What the sources establish
Deal-count share and dollar share measure different things, and the gap between them is the finding here: corporate investors, in this dataset, take part in a minority of deals but a majority of the money, because, as the same table's average deal-value columns show, deals with corporate involvement average far larger checks, $52.6 million in 2024, than the all-venture average of $19.7 million that same year. That gap has widened, not narrowed, since 2018, when corporate-involved deals were 19% of count and 50% of dollars. The landing page's reference to 'corporate strategics and sovereign wealth funds' as joint drivers of 2025's AI capital does not separate the two investor types' contributions, so this dataset cannot say how much of the 58% dollar share is corporate money specifically versus other large check-writers active in the same rounds.
Scope and revision
NVCA's own methodology, cited elsewhere in the same document, classifies 'Corporate Venture Capital' as one of three categories of active VC investors, alongside venture capital and not-for-profit venture firms; a deal counts as having corporate involvement if any investor in the round meets that classification, whether or not the corporate investor led the round or wrote its largest check. The percentages here reflect PitchBook data as of 31 December 2025 and can be revised as later-reported deals are added, particularly for the most recent quarters shown.
The decision in front of you
Editorially: a founder weighing a strategic corporate investor should treat the deal-count and dollar-share figures as evidence that corporate money concentrates in larger, likely later-stage rounds rather than early ones, consistent with the checklist questions a strategic investment typically raises around information rights, rights of first refusal on an acquisition, and exclusivity, none of which this dataset addresses.
- Is a specific proposed round in the smaller share of deals with corporate involvement, or closer to the all-venture typical deal?
- Does the corporate investor's term sheet include information or acquisition rights beyond what a financial investor would ask for?
- Is the 56-58% dollar share concentrated in the handful of very large rounds this dataset's own average-versus-median gap would flag?
A single 'corporate venture capital share' number hides two different measures moving differently; reading count and dollars side by side is what NVCA's own table, not a headline drawn from it, actually supports.
Sources & reading trail
Gives the Corporate VC Investment by Year table: deal count share and dollar share of CVC-involved deals, 2004-2025.
Source published: 9 April 2026 · Retrieved: 16 September 2026
States that 2025 AI-era capital was fueled by corporate strategics and sovereign wealth funds.
Source published: 9 April 2026 · Retrieved: 16 September 2026
Filings, provider reports and official documents establish the record; the scope reading and the decision framing are Venture Trace editorial analysis. This retrospective draft does not imply the site published on the event date.