
The record
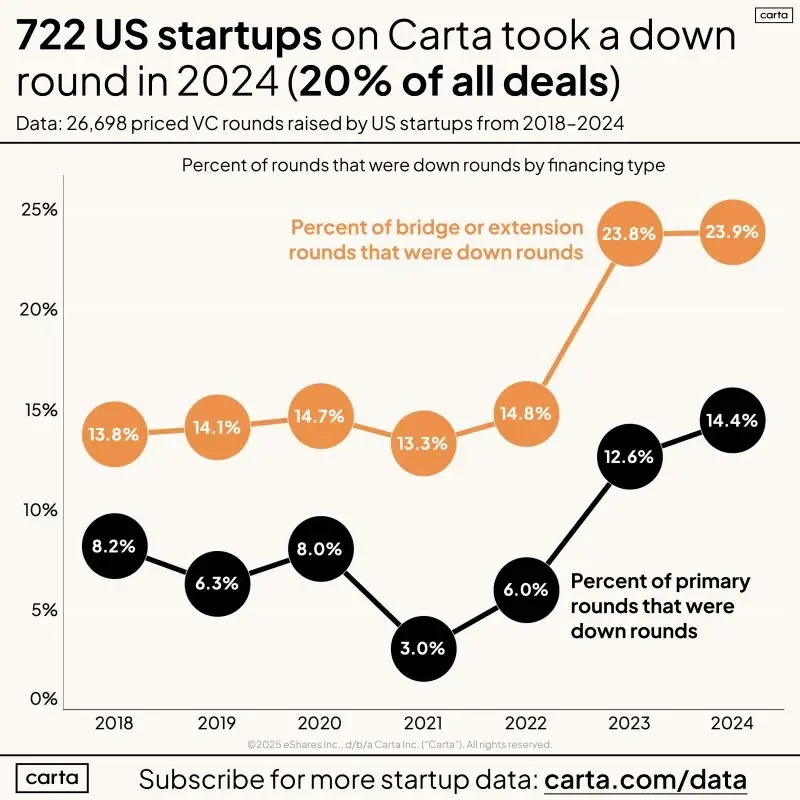
Carta's Insights team reported on 7 January 2025 that 20% of all priced US startup rounds in 2024 were down rounds, a round priced below the company's prior valuation, roughly double what the firm calls a historical average near 10%. The same post separated a second figure: counting only new primary financings and excluding bridge and extension rounds, 14.4% of 2024 rounds were down rounds, which Carta described as the highest share it had recorded. A companion release, Carta's Q4 2024 review, put the fourth-quarter rate at 19% of all new investments, calling it roughly in line with the prior two years.
What the sources establish
The two 2024 figures are not the same measurement: the 20% rate includes bridge and extension financings, where a down valuation is more common by design, while the 14.4% rate isolates new primary rounds only. Carta's data attributes the rise to a specific mechanism, not a general downturn: many 2024 rounds were priced against a valuation set during the 2021 financing boom, and a company raising fresh capital in a more skeptical market had little room to hold that mark. A later post, published 30 July 2025, adds that the rate has begun to recede from a 20-22% range back toward the roughly 10% level Carta treats as typical.
Scope and revision
All three figures come from one provider's own platform data and use Carta's own definition of a down round: a round priced below a company's immediately prior valuation, based on recorded instrument terms rather than external appraisal. The rate is sensitive to which population it is measured against, and Carta's own reporting shows the all-rounds count and the primary-only count diverging by roughly six percentage points in the same year. None of the three posts claims to cover companies outside Carta's cap-table platform, and none adjusts for startups that avoided a priced round entirely by raising a SAFE or note instead.
The decision in front of you
A founder or operator comparing "the down-round rate" across sources should first ask whether bridges are included and whether the base is all priced rounds or primary rounds alone; the two answers here differ enough to change the story from routine to record-setting.
- Does the cited rate include bridge and extension financings, or exclude them?
- What population is the denominator: all priced rounds, or primary rounds only?
- Has a later release from the same provider revised the figure?
A down round is a specific, definable event in a financing document, but the share of the market experiencing one depends entirely on how the count is drawn. Carta's own releases, read together, show the rate rising into 2024 and receding afterward, a trend visible only because the definition stayed constant across each release.
Sources & reading trail
States the 2024 full-year down-round share for all priced rounds (20%) and for primary rounds only (14.4%).
Source published: 7 January 2025 · Retrieved: 16 September 2026
States the Q4 2024 down-round share (19% of all new investments) and attributes the trend to 2021-era valuation overhangs.
Source published: 12 February 2025 · Retrieved: 16 September 2026
States the historical baseline down-round rate (about 10%) and that the 2022-2024 rate of 20-22% has begun to recede.
Source published: 30 July 2025 · Retrieved: 16 September 2026
Filings, provider reports and official documents establish the record; the scope reading and the decision framing are Venture Trace editorial analysis. This retrospective draft does not imply the site published on the event date.