
The record
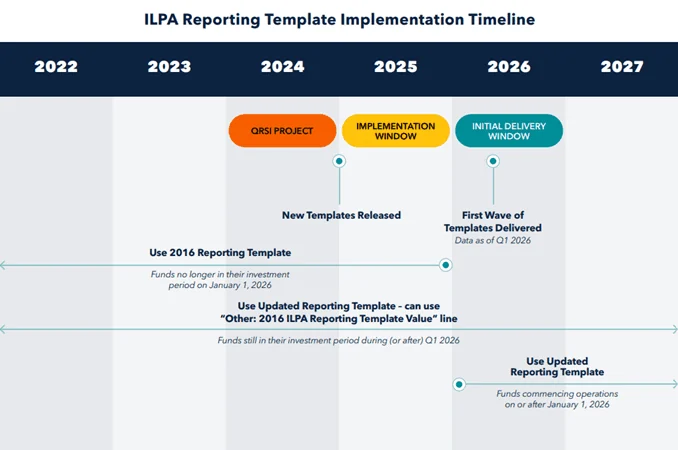
ILPA maintains a standardised Reporting Template addressing fee, expense and carried-interest disclosure across private equity and venture funds, published at ILPA's own ILPA Reporting Template page. That page, as retrieved on 16 September 2026, states the template 'promotes more uniform reporting practices in the private equity industry related to fees, expenses and carried interest.' An updated version 2.0 was developed through 2024 as part of ILPA's Quarterly Reporting Standards Initiative and released in January 2025, described in a companion video walkthrough page dated 27 February 2025.
What the sources establish
ILPA's page states the updated template is intended to replace the prior 2016 ILPA Reporting Template on a go-forward basis for funds still in their investment period during the first quarter of 2026, or for funds commencing operations on or after 1 January 2026, while GPs may continue using the 2016 template for funds no longer in their investment period as of that date. ILPA also publishes a redline comparing the definitions in the 2016 and updated templates, and separate guidance documents and formula overviews accompanying the new version. The walkthrough page frames the release as one deliverable of a broader initiative that also produced a companion Performance Template.
Scope and revision
Both the template and its 2016 predecessor are voluntary documents; ILPA's own pages describe endorsement by GPs and LPs rather than mandatory use, and a fund's actual reporting practice depends on what its governing documents or side letters require, not on the template's existence. Because two versions are live simultaneously during the 2025-2026 transition ILPA describes, a reader comparing fee disclosures across funds should check which template version, if either, a given GP actually follows before treating two funds' reported figures as built on the same categories. The template's fee and expense definitions are ILPA's own, distinct from any regulatory chart of accounts.
The decision in front of you
An LP or analyst reviewing a fund's quarterly reporting can check whether it follows the updated ILPA template, the 2016 version, or neither, using the transition dates ILPA's own page states, before comparing fee or carried-interest figures across managers. This is a description of what ILPA's materials say about the template's status, not confirmation that any specific GP has adopted it.
- Which ILPA template version, if any, does the fund's reporting actually follow, based on its investment-period status against the stated 2026 transition dates?
- Are fee, expense and carried-interest figures from two different funds defined under the same template version before being compared?
- Has the GP publicly endorsed the template, or is 'ILPA-aligned' reporting language unverified against actual disclosures?
A standardised template only standardises reporting where a GP has actually adopted it, and ILPA's own materials treat that adoption as a choice, not a filing obligation.
Sources & reading trail
ILPA's own page describing the template's purpose and the 2025-2026 transition from the 2016 version to the updated version.
Source published: Not established · Retrieved: 16 September 2026
Confirms the January 2025 release of the updated template as part of ILPA's Quarterly Reporting Standards Initiative.
Source published: 27 February 2025 · Retrieved: 16 September 2026
Filings, provider reports and official documents establish the record; the scope reading and the decision framing are Venture Trace editorial analysis. This retrospective draft does not imply the site published on the event date.